Regularly export histories from every platform and wallet, retain price and fee evidence, and link internal transfers with transaction identifiers. Taxable events, valuation methods and reporting duties depend on jurisdiction and personal status.
Every source must be reconciled.
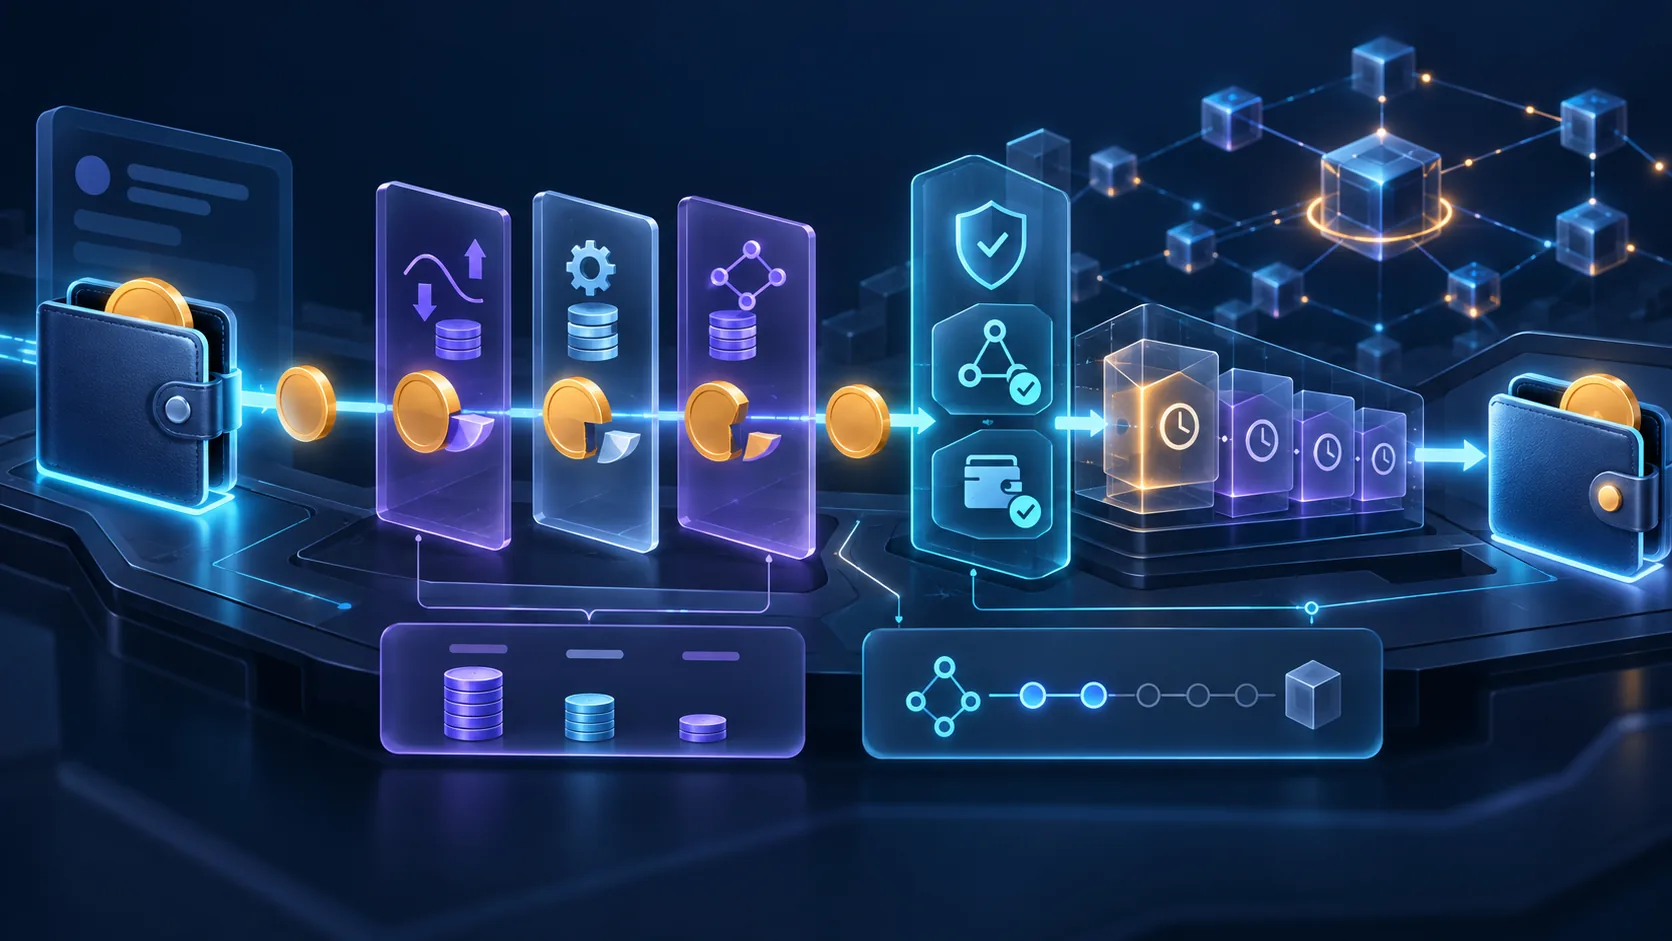
Date, asset, quantity, value and fees.

An internal transfer should not be assumed.
Inventory every source
List platforms, wallets, blockchains, bank accounts and discontinued services. Export native files before closure and record the period, timezone and unit used by each statement.
Normalize operations
For each movement, keep timestamp, nature, sent and received asset, quantity, reference value, fees, address and transaction ID. Keep failed operations if they incurred fees.
- Retain the raw file
- Work on a normalized copy
- Document manual corrections
Reconcile internal transfers
A withdrawal from a platform may match an entry in your wallet and not be a disposal. Link both sides by network, amount, time and ID while accounting for fees and wrapped tokens.
Apply local rules
Identify tax residence, private or business status, taxable events, cost method and retention periods. Seek qualified advice for complex cases, especially DeFi, staking, airdrops, bridges and losses.
- Check the current rule version
- Keep calculation and source
- Archive the filing and evidence
Reconstruct a usable history
A platform export may omit transfers to other wallets or DeFi activity. Match each event with date, asset, quantity, fees, value and transaction identifier.
- Retain evidence and the valuation method used.
- Check applicable rules with the authority in your country.
Practical case: decision and limits
Moving an asset between your own accounts requires matching withdrawal and deposit using hash, network, time and amount after fees. Keep both statements and valuation sources; incomplete exports can hide transfers or swaps. Tax treatment of fees and operations depends on jurisdiction. Reconciliation alone does not determine tax owed.
A concrete verification
Reconcile opening, movements and closing by asset: a formatted export can omit a wallet.
Preserve exact quantities in supporting records
Keep the raw integer, decimals used, contract, network and transaction reference together. This lets you reconstruct quantity independently of a rounded display. Hypothetical example: 1234567 units at 6 decimals give 1.234567 tokens; a statement limited to two decimal places hides part of the quantity.
- Keep the source record and exact quantity before display rounding.
- Unit conversion determines neither tax valuation, acquisition cost nor legal treatment.
Reconcile a platform statement with your own records
In the EU, DAC8 sets collection and reporting duties for reporting providers starting with the 2026 reporting period. The OECD’s CARF also provides for information exchange between tax authorities where implemented. If a provider supplies an annual statement, compare the period, currency and aggregated entries with your raw exports. Keep evidence of movements to your own wallets and any fees charged separately. Check the applicable rules in your tax residence before preparing your personal filing.
Convert token units without rounding →
Minimum record per operation
| Field | Example evidence | Purpose |
|---|---|---|
| Timestamp | Export and explorer | Order and reporting period |
| Quantities | Raw statement | Inputs, outputs and balance |
| Valuation | Dated method and source | Calculation basis |
| Fees | Receipt and transaction | Cost or expense under local rules |
Frequently asked questions
Is a block explorer enough?
No. It shows on-chain movements but not always identity, acquisition price or internal platform trades.
Should raw files be kept?
Yes. They allow recalculation and support the origin of a correction.
Is this tax advice?
No. It is a general record-keeping method; rules must be checked in each jurisdiction.
Verifiable sources
 OECD: Crypto-Asset Reporting Framework
 ESMA: Crypto-assets and investor information
 Bitcoin.org: What you need to know
 ERC-20: Token amounts, decimals and allowances
- EUR-Lex: DAC8 crypto-asset reporting
Independent educational content reviewed against primary documentation. No personalized recommendation or promise of returns. Updated November 15, 2026
Prepare and continue reading
Useful background
- Buy your first cryptocurrency with a clear method
Before buying, verify the provider’s legal identity, availability in your country, full costs and withdrawal process. Secure the account, start small and test a transfer to a wallet you control before committing more.
- How to read a transaction in a block explorer
Copy the transaction hash from your wallet, open a trusted explorer for the correct network, then compare status, addresses, asset, amount, fees and confirmations. Never enter a recovery phrase.
Continue to the next step
- Blockchain privacy: what is public, traceable or selectively disclosed
An address is not necessarily a name, yet its public history can be clustered and linked to identity through a service, reuse, publication or network metadata. Privacy is a set of practices, not a switch that guarantees anonymity.
- Crypto backup and inheritance: preserve access without exposing keys
A sound plan separates inventory, secrets and instructions. It uses protected redundant copies, distinct people or roles, a tested recovery procedure and regular reviews. Never keep the recovery phrase, access code and complete instructions together.