Liquidity provision exposes you to asset prices, rebalancing and protocol risk. Displayed fees alone are not a net return.

The same starting assets
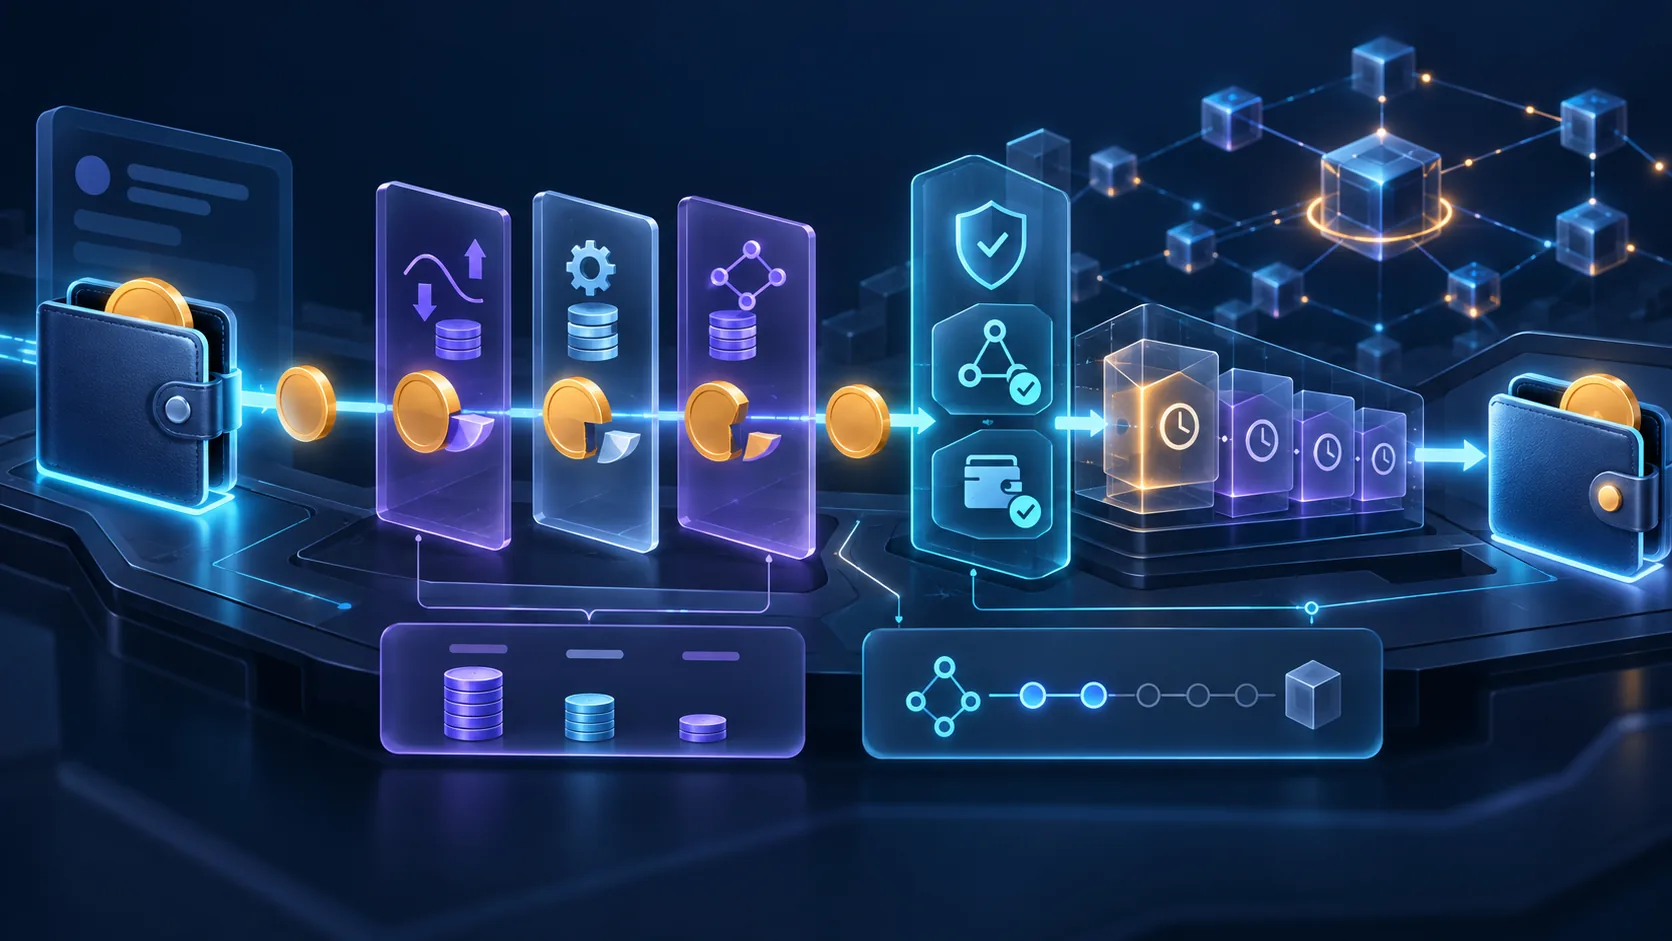
Hypothetical 50/50, no fees
Relative price ratio
Choose a fair benchmark
Start both comparisons with identical asset quantities at the same time. Position results include remaining asset value, earned fees, incentives and costs. Comparing only initial value can hide underperformance against holding. Annualising a brief period does not predict future volume or reward-token value.
Read a constant-product example
Initially 1 A costs 100 B; provide 1 A plus 100 B. If A rises to 400 B, an ideal 50/50 constant-product position holds 0.5 A and 200 B, worth 400 B. Holding the original quantities would be worth 500 B. The position gains from the initial 200 B yet trails holding by 20%. This hypothetical ignores fees, costs and operational differences.
Understand formula limits
For that ideal model only, relative difference is 2√r/(1+r) − 1, where r is the relative price change. At r = 2 or 0.5 the difference is about −5.72%; at r = 4 it is −20%. Different weights, concentrated liquidity, fees and unusual tokens change results. The label impermanent does not promise prices will return.
Monitor concentrated ranges
Concentrated positions supply liquidity within chosen bounds. Outside the range they no longer supply active liquidity at the current price and can become predominantly one asset. Range width, price path and exit timing matter. Repositioning can require transactions and swaps, adding costs and operational exposure.
Inspect dependencies
Verify network, contract addresses, requested approvals, token behaviour and withdrawal rules. Transfer-fee tokens and blocking controls can alter expected operation. Audits and volume are not security guarantees. Temporary incentives or illiquid rewards should be distinguished from funds actually withdrawable.
Measure the exit result
Record starting quantities, benchmark prices, earned fees, network costs and final quantities. Compare with the current value of initial assets and your liquidity needs. Underperforming holding can coexist with an absolute gain; prices can also produce the opposite result. Fee income is neither guaranteed nor automatically sufficient to offset divergence.
A concrete verification
Compare net outcome with initial holding: a euro gain can still underperform that benchmark.
Concentrated liquidity is not always active
A concentrated position provides liquidity within a price range. When price moves outside that range, the position no longer supplies active liquidity or earns swap fees in that capacity. It may consist entirely of one asset.
- Composition depends on quote direction and the price location.
- Re-entering the range does not erase costs already incurred.
Worked example: a 2,000–2,200 range
In this fictional example, price reaches 2,300: a position covering 2,000 to 2,200 is out of range. Recentering requires reviewing inventory and may involve swaps and network fees.
- Compare the net result with holding the original assets, including costs.
- A narrower range also increases the risk of needing frequent intervention.
Reconcile the pool position and accrued fees
In Uniswap v2, the liquidity providers’ share of swap fees increases the pool reserves. In Uniswap v3, fees are separately claimable for a position and accrue while its liquidity is in range. To measure the exit value, reconcile the assets that can be withdrawn, fees still claimable and transaction costs. Check whether the interface already includes the fees in its estimate before adding them.
Scenarios and model limits
| Situation | Interpretation |
|---|---|
| Hypothetical 50/50, no fees: r = 1 | Difference from holding: 0%. |
| Same model: r = 2 or 0.5 | Difference: about −5.72%. |
| Same model: r = 4 | Difference: −20%, even with an absolute gain. |
Frequently asked questions
Do high fees erase divergence?
They may offset it over a period, but not reliably. Compare complete results after costs with holding.
Does the 50/50 formula apply everywhere?
No. It describes an ideal constant-product model without fees, not concentrated ranges directly.
Do out-of-range positions earn the same fees?
An out-of-range position no longer supplies active liquidity at the current price. Exact rules depend on the protocol.
Verifiable sources
- Uniswap: Understanding liquidity returns
- Uniswap: Concentrated liquidity
 Ethereum.org: DeFi risks and mechanisms
- Uniswap: Liquidity fees
Independent educational content reviewed against primary documentation. No personalized recommendation or promise of returns. Updated November 15, 2026
Prepare and continue reading
Useful background
- Explore decentralized finance without ignoring risk
DeFi provides exchange, lending or yield through smart contracts. It can reduce some intermediaries but adds code, oracle, governance, liquidity, bridge, admin-key and signing risks.
- Liquidity and volatility: understand the price you can execute
Liquidity is the ability to buy or sell without moving the price sharply. Review spread, depth at several distances, credible volume, fragmentation, order size and withdrawal conditions. Historical volatility does not cap the next move.
Continue to the next step
- Slippage: calculate minimum output before a swap
For a fixed-input swap, compare the quote, minimum output and total cost. Tolerance is neither a certain fee nor a security guarantee. Do not increase it without understanding why execution failed.
- Tokenomics: read supply, allocations and unlocks
Tokenomics covers the rules for creating, distributing and using a token. Check maximum and circulating supply, issuance, burns, initial allocations, vesting, concentration, utility and rights. Announced scarcity does not guarantee demand, liquidity or value.